
For the period ending 9/25/2026
Market Review
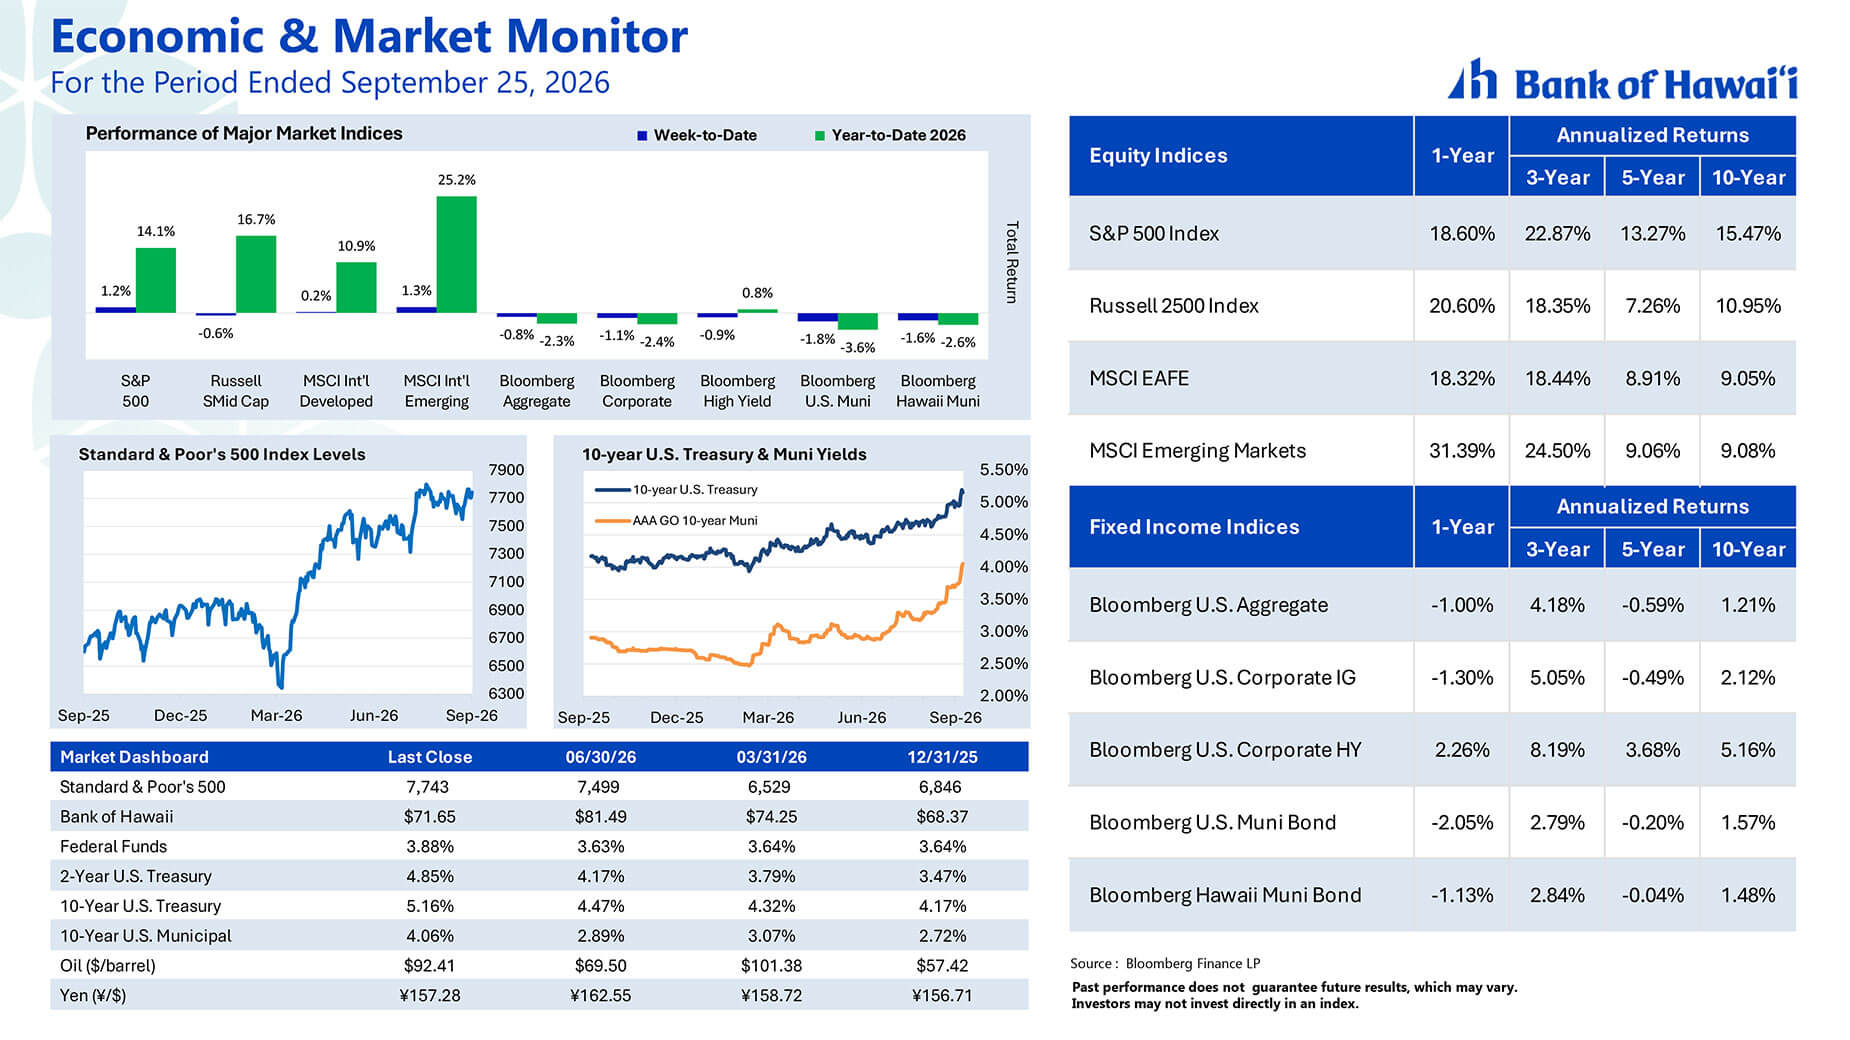
Equity Markets Advanced on Strong Economic Data and Easing Oil Prices: U.S. equities finished the week higher, supported by a series of encouraging economic reports that reinforced confidence in the strength of the domestic economy. Lower oil prices also helped, with West Texas Intermediate (WTI) crude closing on Friday at $92.41 per barrel, down 7.9% for the week. The price drop was largely in response to Iran signaling that it was open to resuming negotiations with the United States and reopening the Strait of Hormuz to commercial shipping.
The S&P 500 Index gained 1.2% for the week, bringing its year-to-date return to 14.1%. Leadership came from the technology, communication services, and industrials sectors. Overseas, developed markets also posted gains, with the MSCI EAFE Index rising 0.2%, while the MSCI Emerging Markets Index advanced 1.3%. Year-to-date returns for the two indexes were 10.9% and 25.2%, respectively.
The Economy Strengthened in September: The S&P Global Flash (preliminary) Composite Purchasing Managers' Index (PMI) rose to 58.4 from 56.0 (final) in August, marking its highest reading in more than five years. This came as a significant surprise to economists. Index readings above 50 indicate expansionary economic conditions. The improvement was primarily driven by robust growth in the services sector, but manufacturing activity also advanced. Encouragingly, new orders for the composite PMI increased at their fastest pace in nearly four and a half years, which bodes well for future growth.
Interest Rates Climbed Further: U.S. Treasury security yields moved higher in reaction to the strengthening economy. Two-year and 10-year U.S. Treasury notes rose 11 basis points and 16 basis points, respectively, to close at 4.85% and 5.16% on Friday. Higher rates weighed on fixed-income markets, with the Bloomberg U.S. Aggregate Bond Index down 0.8% and the Bloomberg U.S. Municipal Bond Index down 1.8% for the week. Respective year-to-date losses for the indexes were 2.3% and 3.6% as of Friday.
Unemployment Claims Dropped: The Department of Labor reported that initial jobless benefit claims for the week ending September 19 were 197,000, down 1,000 from the prior week and below the Bloomberg median estimate of 200,000. Continuing claims for the week ending September 12 were 1.72 million, down 11,000 and also below the median estimate of 1.74 million.
Outlook
The economy is exhibiting surprising resilience in the face of ongoing geopolitical instability, sharply higher oil prices, elevated inflation, and rising interest rates. Heavy AI-related capital spending, which is showing no signs of slowing anytime soon, is providing a powerful counterforce to the headwinds that emerged this year. With robust corporate earnings growth supporting the equity market, its general uptrend may continue, with a boost possible if hostilities between the U.S. and Iran ease. Oil prices and inflation have taken their toll on fixed-income markets this year, but high-grade bonds are currently trading with the highest yields in over 19 years. This is providing investors with a generous spread above current and anticipated inflation.
PCE on Wednesday: The Bureau of Economic Analysis will release the Federal Reserve’s preferred inflation measure, the Core Personal Consumption Expenditures (PCE) Price Index for the month of August. The median estimate of economists surveyed by Bloomberg is for a year-over-year increase of 3.3%, unchanged from July’s reading. The PCE report is generally not a market mover because it is largely derived from data contained within previously released Consumer Price Index and Producer Price Index reports. Although the PCE is expected to stabilize in August, it remains well above the Fed’s 2% target, keeping upward pressure on the fed funds rate. As of Friday, fed funds futures implied a 78% probability that the fed funds rate will be hiked by another 25 basis points by the end of this year.
September Employment Reports on Friday: The Bureau of Labor Statistics will release September’s non-farm payrolls, unemployment, and wage growth data. Bloomberg median forecasts call for non-farm payrolls to increase by 90,000 from August’s level, the unemployment rate to hold steady at 4.1%, and year-over-year wage growth of 3.2%. The change in payrolls, which has proven very difficult for economists to predict, has the potential to move markets. A much higher-than-anticipated report could put upward pressure on interest rates, while a much weaker report could cause rates to drop.
This material is provided for educational purposes only and is not intended to be relied upon as a forecast, research, or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities or to adopt any investment strategy. Bank of Hawaii and its affiliates do not provide tax, legal or accounting advice. This material is not intended to provide, and should not be relied on for, tax, legal, or investment advice. You should consult your own tax, legal, accounting or financial professional before engaging in any transaction. Neither the information nor any opinions expressed herein should be construed as a solicitation or a recommendation by Bank of Hawaii or its affiliates to buy or sell any securities, investments, or insurance products. Investing involves market risk, including possible loss of principal, and there is no guarantee that investment objectives will be achieved. Past performance is not a guarantee of future results.
